
FIRST-TIME BUYER MORTGAGE ADVICE
IN PLYMOUTH & THE SOUTH HAMS
YOUR FIRST HOME STARTS WITH A CLEAR PLAN
Buying your first home brings plenty of questions. How much can you borrow? Is your deposit enough? What will the monthly payments be? At Mewstone Mortgage Advice, we help first-time buyers in Plymouth and the South Hams understand their options before they commit.
Charlie provides friendly, straightforward support, from planning your budget and preparing an Agreement in Principle to your mortgage application and completion. Her estate agency background helps her explain the wider buying process, as well as the mortgage.
BOOK AN APPOINTMENT
LET’S TALK ABOUT YOUR FIRST HOME
Choose a convenient time to speak with Charlie about your plans.
- Visit our Plymouth office or ask about a home visit.
- Phone, video or face-to-face appointments.
- Clear answers about your next steps.
Why Get Expert Advice Before Buying Your First Home?
Your first mortgage is about more than finding a rate. Lenders assess income, spending, credit history and properties differently. Advice early on can help you set a realistic house-hunting budget and understand which options may suit your circumstances.
- Check borrowing and monthly affordability before making an offer.
- Understand deposits, buying costs and low-deposit options.
- Compare the overall cost of suitable mortgages, including fees.
- Prepare documents and understand the application process.
- Get support with questions as your purchase progresses.
Whether you are looking in Plympton, Plymstock, Ivybridge or elsewhere across Plymouth and the South Hams, start with your finances and plans, rather than a headline borrowing figure.
READY TO UNDERSTAND YOUR OPTIONS?
ASK FOR A FIRST-TIME BUYER APPOINTMENT WITH CHARLIE.
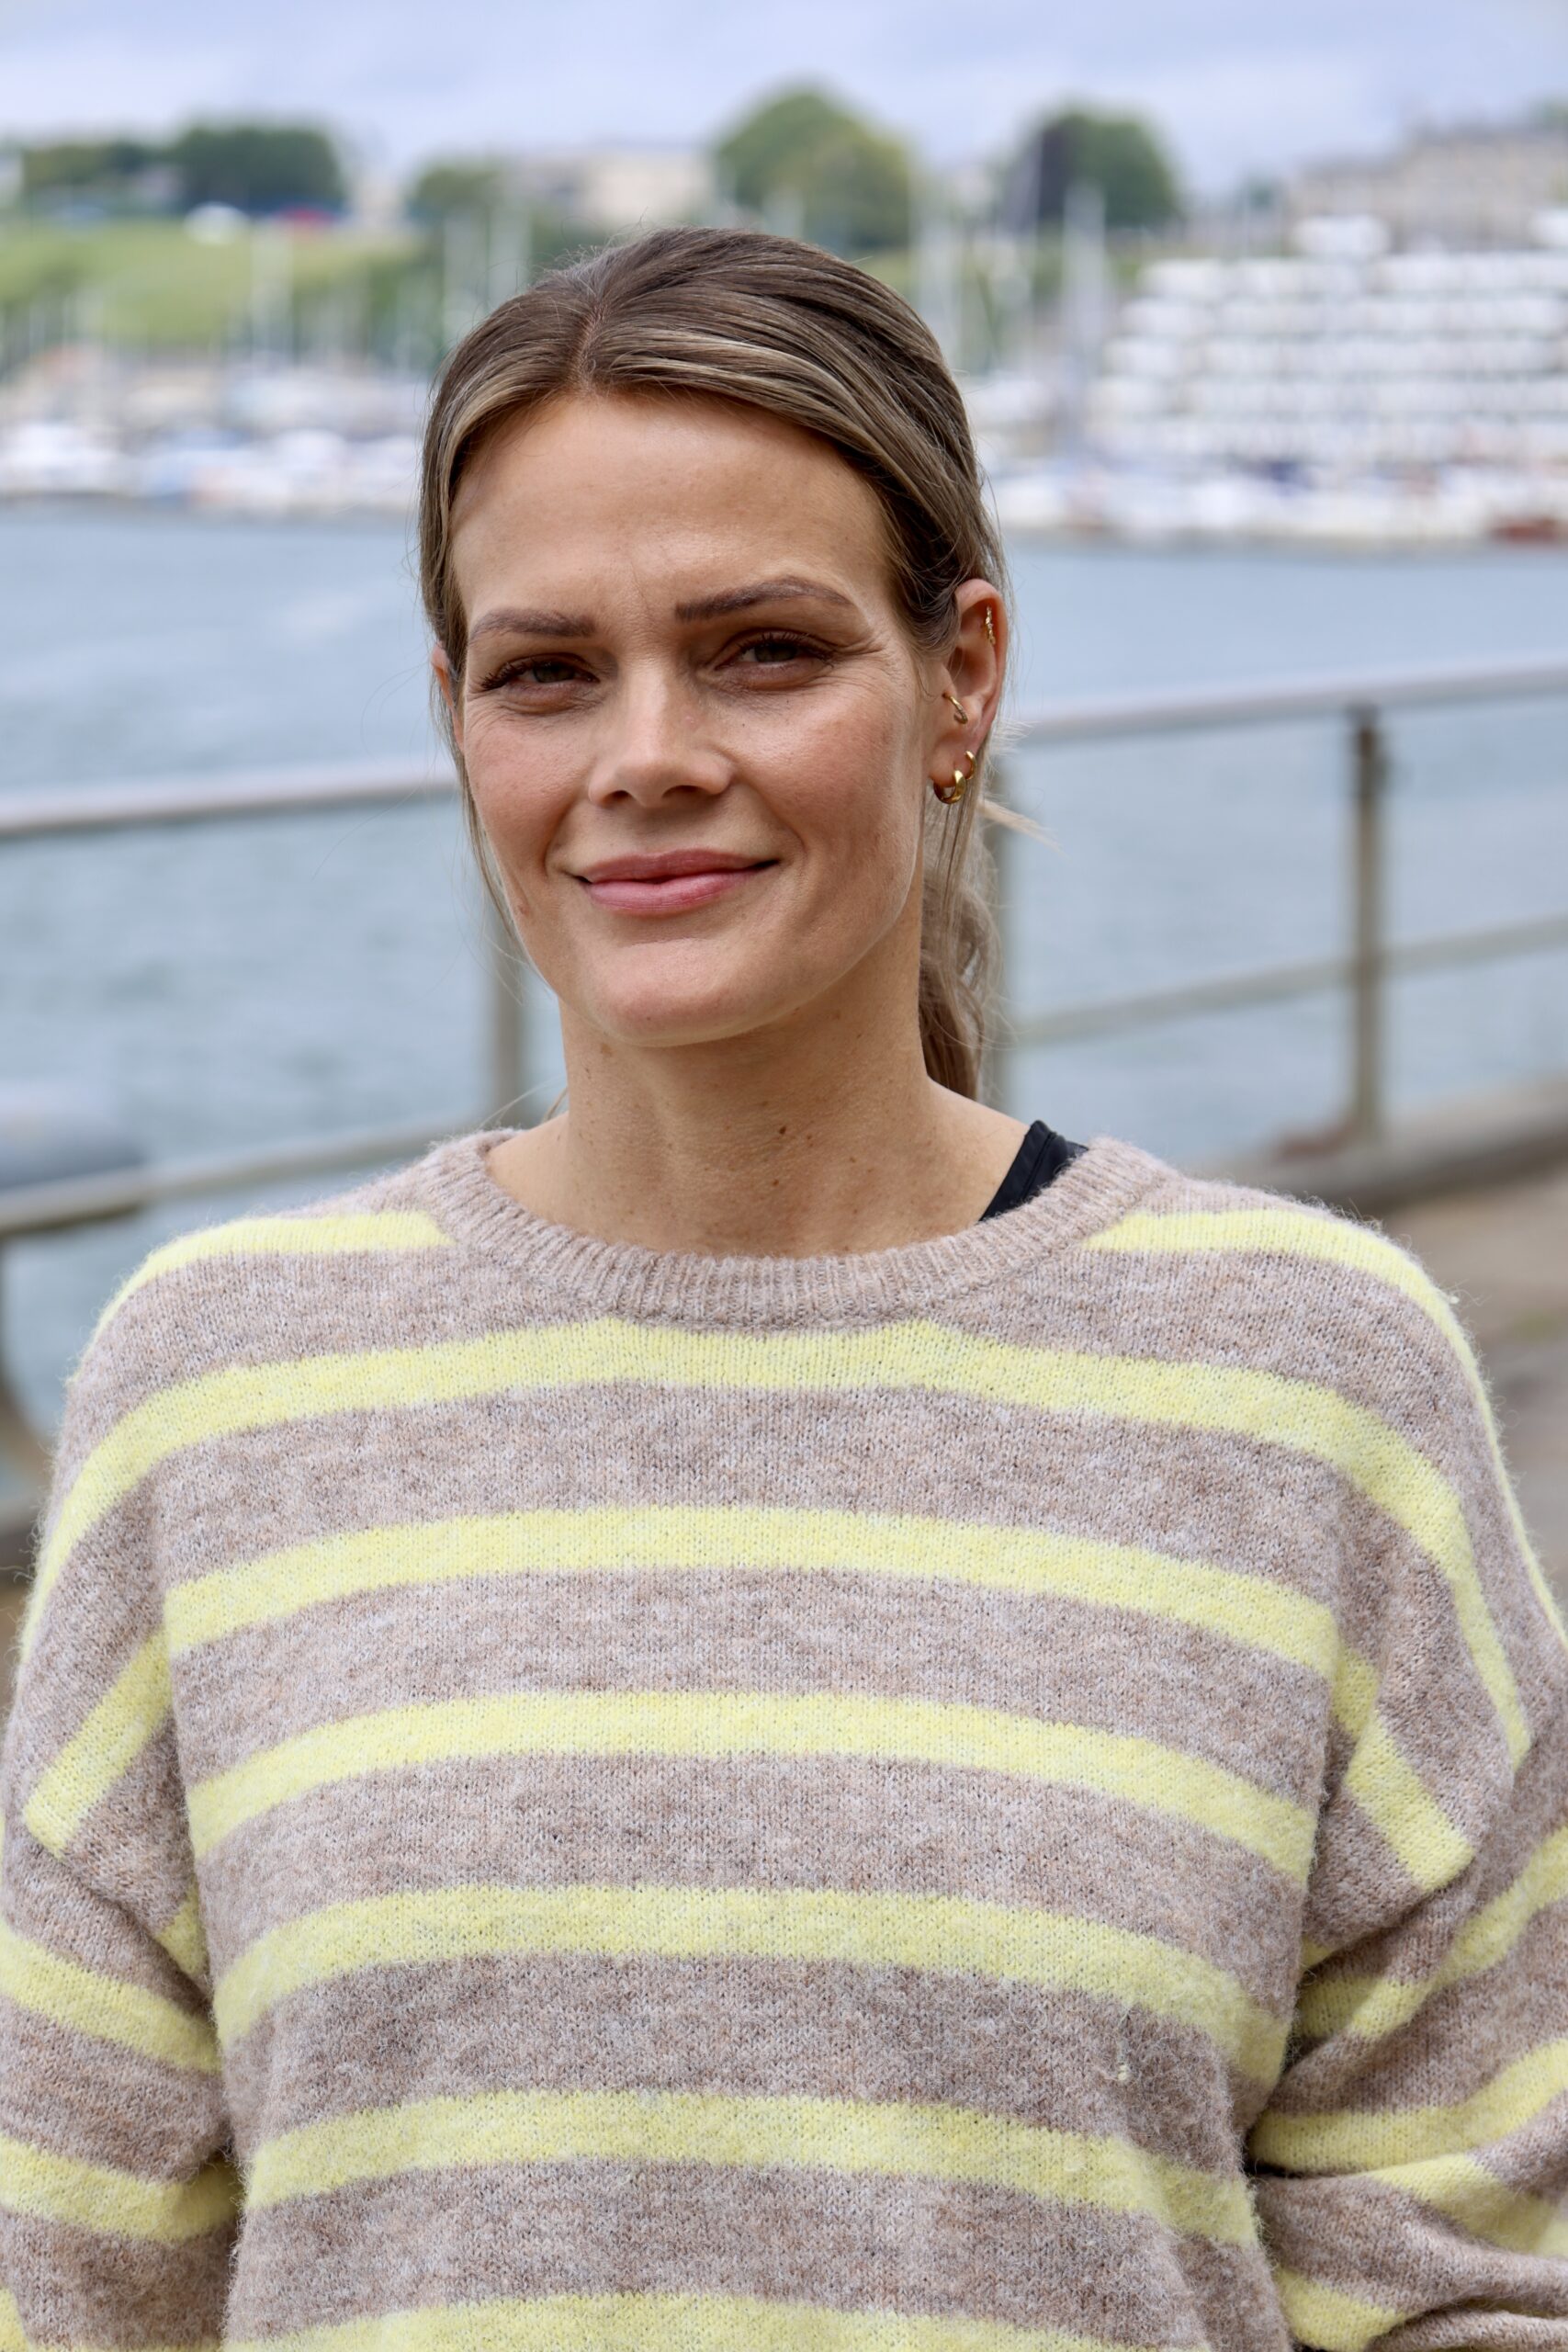
MEET CHARLIE: SUPPORT THROUGH YOUR FIRST PURCHASE
Charlie helps first-time buyers and home movers across Plymouth and the South Hams. With an estate agency background, she understands that finding a property, making an offer and arranging the mortgage are all connected.
She will talk through your priorities, explain the mortgage options and help you prepare for the next step. For families buying their first home, this includes considering childcare costs, existing commitments and a monthly budget that leaves room for everyday life.
You can meet the team at Argosy House, Longbridge Road, Plymouth, PL6 8LD, or discuss phone and video appointment options. Learn more about our advisers and explore our mortgage advice services.
How Much Can I Borrow, and What Will It Cost?
We look at your deposit, income, regular commitments and the type of property you want to buy. Together, these help establish a realistic budget. A calculator can be a starting point, but it cannot confirm that a lender will accept your application.
How Much Could You Borrow?
Lenders consider your income, committed spending, credit history, deposit and mortgage term. Overtime, bonuses, self-employed earnings and childcare can affect the result. There is no single salary multiple that guarantees a mortgage.
Charlie can assess your circumstances and help you prepare an Agreement in Principle. This is an initial indication of lending, not a mortgage offer: the lender must still assess your application and the property.
What Deposit Will You Need?
A 5% deposit is a common starting point, but other routes may be available. On a £200,000 purchase, 5% is £10,000 and 10% is £20,000. A larger deposit reduces the loan needed and may improve the mortgage options available.
Savings or a permitted family gift may contribute, subject to lender checks. Keep money aside for fees and moving costs too. Smaller deposits increase the risk of owing more than your home is worth if prices fall.
What Will Your Monthly Payments Be?
Payments depend on the amount borrowed, interest rate, term and repayment method. A longer term can reduce the monthly payment but usually increases total interest. A fixed rate lasts for an agreed period; payments may change afterwards.
We will compare suitable options and explain your personalised illustration, including fees, early repayment charges and what happens when an initial deal ends. Budget for Council Tax, utilities, insurance, maintenance and any service charges alongside the mortgage.
YOUR FIRST HOME: FROM PLANNING TO COLLECTING THE KEYS
1. Discovery Call
Start with a friendly conversation about where you are now and what you hope to buy. Charlie will explain how Mewstone works and the support available as you plan your first home.
2. Get Mortgage Ready – Get Prepared
We get to know your circumstances and check your documents before advising you. Use your secure client portal to share information about your income, spending, deposit and commitments.
3. Advice & Recommendations
Charlie will explain what you may be able to borrow, the deposit and fees to budget for, and your likely monthly payments. We will recommend suitable mortgage and protection options and explain the reasons for our advice.
4. Agreement in Principle
Once your information is ready, we can approach a suitable lender for an Agreement in Principle. This is a provisional lending indication, subject to the lender’s checks, your circumstances and the property. It can help show estate agents that you are prepared to buy.
5. Offer Accepted – Mortgage Application Submission
When your offer on a home is accepted, we review your documents and circumstances, confirm our advice and help submit the full mortgage application. We liaise with the lender and help you respond to any requests for further information.
6. Mortgage Offer
If the lender approves your application, it issues a mortgage offer setting out the terms and conditions. We check the details with you so you understand what has been offered and what needs to happen next.
7. Exchange & Completion
Your solicitor handles the legal work and explains when you are ready to exchange contracts, which makes the purchase legally binding. We help you check the agreed protection arrangements and mortgage requirements. On completion, the funds are transferred and you can collect the keys.
8. The Journey Continues
Our support continues after you move in. Speak to us when your circumstances change, you plan your next move or your mortgage deal approaches its end. We can help review your mortgage and protection as your needs develop.
Explore the full Mewstone Client Journey to see how we support you at each stage.
Watch Our First-Time Buyer Video
First-Time Buyer Schemes & Low-Deposit Options
0% Deposit: Mortgages for Eligible Renters
Some lenders offer mortgages without a cash deposit to eligible applicants. Skipton’s Track Record option considers rental payment history alongside its other checks. You still need to meet affordability, credit and property requirements and budget for legal and moving costs. A 100% mortgage is not available to everyone.
5% Deposit Mortgages
A 95% mortgage means borrowing 95% of the property’s value and providing the other 5% as your deposit. Acceptance depends on the lender’s assessment. We can compare suitable options and explain how the deposit affects your borrowing and costs.
£5,000 Deposit Mortgages
A fixed £5,000 deposit may be possible with certain lender products. For example, Accord’s current option is for eligible first-time buyers purchasing qualifying existing properties, with purchase-price and loan limits; new builds are excluded. This is not a promise that £5,000 will be sufficient for every buyer or property. Other buying costs are additional.
Your First Home: Announced 2.5% Deposit New-Build Scheme
The government has announced Your First Home for eligible new-build purchases in England. It combines a deposit of at least 2.5%, a 20% government equity loan and a repayment mortgage. Applications are expected to open in February 2027; it is not yet open.
The equity loan is interest-free for the first five years, but it must be repaid and is not a grant. Eligibility, local price caps and participating developers and lenders apply. Read the official Your First Home guidance for current details.
Shared Ownership
Shared ownership involves buying a share of a home and paying rent on the remaining share. The deposit is usually 5–10% of the share you buy, rather than the full property value. You must allow for mortgage repayments, rent and service charges, as well as repair responsibilities and the costs of buying more shares. Availability and eligibility vary.
Read the government’s shared ownership guidance. Charlie can help you explore the mortgage side and understand how the combined payments fit your budget.
Scheme information checked 13 November 2026. Products and criteria can change. Availability does not mean that an option is suitable for your circumstances.
Buying your first home in Plymouth or the South Hams? Let’s plan your next step.
First-Time Buyer Mortgage FAQs
How much can a first-time buyer borrow?
Your borrowing depends on income, spending, credit commitments, deposit, term and the property. Different lenders assess these differently. We will look at your circumstances before discussing a realistic range, rather than promising a set income multiple.
Can I buy with a small deposit or no deposit?
Potentially. Options include 5% deposits, fixed £5,000 deposit products and some no-deposit mortgages for eligible renters. Each has its own criteria and restrictions. You will still need to budget for buying costs, and a larger deposit can improve your options. Read our deposit guide.
What fees and buying costs should I budget for?
Allow for your deposit, solicitor or conveyancer charges and searches, a survey, any lender product or valuation fees, moving costs and Stamp Duty where applicable. Your solicitor should confirm your tax position. Buildings insurance and ongoing homeownership costs also need a place in your budget.
Our fee for a new mortgage is £499, payable at application. We will confirm the applicable fee and when it becomes payable before you commit. Lender and third-party costs are separate. Adding an eligible lender fee to a mortgage increases borrowing and the interest paid on it.
What documents will I need?
Typically, identification, address evidence, recent bank statements, income evidence and proof of the deposit’s source are required. Self-employed applicants and people using gifted deposits may need additional documents. We will give you a checklist for your circumstances. See our mortgage appointment document guide.
Can I apply if I am self-employed or have credit difficulties?
These circumstances do not automatically rule out a mortgage, but they can affect the lenders, deposit and products available. Tell us about your income and credit history early so we can assess suitable options. Do not assume that a low-deposit product will accept every credit profile.
When should I speak to Charlie, and how long does buying take?
Ideally, speak to Charlie before making an offer. You can discuss your plans even if you are still saving. Timescales depend on the lender, property, legal work and any chain, so completion dates cannot be guaranteed. Contact Mewstone and ask for Charlie to arrange your next step.
First-Time Buyer Guides & Next Steps
Start with our first-time buyer guide, then speak to us about the options that fit your budget.
FOLLOW US ON INSTAGRAM


Mewstone Mortgage Advice LTD (FCA ref 947355) is an appointed representative of New Leaf Distribution LTD (FCA ref 460421) which is authorised and regulated by the financial conduct authority (FCA).
New Leaf Head Office Garfield House, 165-167 High St, Rayleigh SS6 7QA. Co registration Number 5520001.
Mewstone Mortgage Advice LTD Head Office: Argosy House, Longbridge Road, Plymouth, PL6 8LD. Co registration Number 12959322
Your home is at risk if you fail to keep up payments on your mortgage or any other loans secured against it.
Buy to Let mortgages and Commercial Lending are not usually regulated by the Financial Conduct Authority.
To view our Complaints Procedure, click here.
